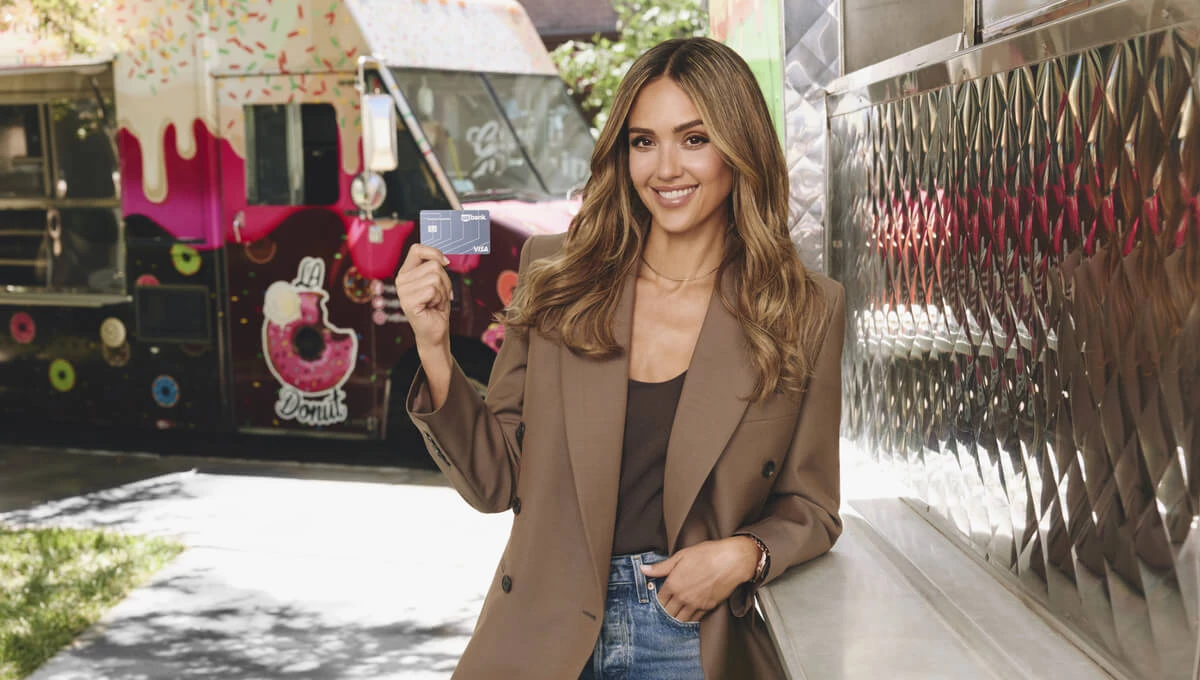

Small business owners spend plenty of hours on paperwork, so U.S. Bank hired a familiar face to make its newest card pitch worth a look.
The bank launched the "Business Essentials Visa Card" and the "Business Essentials Plus Visa Signature Card," with BarkleyOKRP leading the campaign.
Actress Jessica Alba, an experienced small business owner, debuts as the bank's new spokesperson.
She fronts an 18-month national campaign across connected TV, online video, digital, and out-of-home, in a category where card offers tend to look alike.
The audience already borrows, with 86% of small employer firms using financing on a regular basis, according to the Federal Reserve's 2025 survey.
Both cards offer unlimited 2% cash back on eligible purchases.
Owners who hold qualifying balances in a U.S. Bank business checking account earn up to 2.5% on the standard card and up to 3.5% on the Plus.
The standard card has no annual fee, while Plus costs $295 a year and adds 5% cash back on a company's top spend category, up to $200,000 annually.
Courtney Kelso, senior executive vice president of payments, consumer, and small business, tied the launch to the size of the segment.
Small business owners employ over 61 million Americans and contribute nearly half of the nation's GDP, she said.
"They deserve financial products that reward their ambition and empower them to succeed," Kelso added.
Pricing does the targeting here, since the top rate only pays out for owners who park deposits at the bank.
Product design decides who a rewards program actually serves, even before the ads run.
A $295 Ticket to 3.5% Cash Back
The cards draw on the bank's wider small business services.
Both come with the Spend Management platform for receipt capture and card spend tracking.
Owners can also set card controls and connect the platform to their existing accounting software.
Both also include U.S. Bank Extend Pay, a fixed-fee payment plan for large purchases.
Cash back redemption is where the banking relationship comes in.
Owners can send rewards straight into a qualifying business checking account or take them as a statement credit on the card.
U.S. Bank says this gives owners a way to lower operating costs by reinvesting in the business.
The bank also wants the cards to help owners centralize expenses and protect against fraud.
This way, they can spend more time growing the business than managing it.
Rewards that route straight back into a checking account give the bank a second hook once the welcome bonus is spent.
A product launch holds customers when the payout changes how they run the business day to day.
A Case for Bundled Banking
Bundling is the mechanic here, and small business owners rely on cards to keep operations moving.
Credit cards and loans are the most common products among the 86% of employer firms that use financing regularly.
The card is already in the wallet, so the fight is over which bank holds the rest of the relationship.
U.S. Bank stacked a recognizable spokesperson, a flat 2% rate, and a checking incentive into one offer to win that relationship.
A brand gunning for the same effect should look at these three moves:
- Tie the higher reward to a second product: A bonus rate for checking balances gives customers a reason to consolidate their banking.
- Cast someone who has done the customer's job: Alba's background as a small business owner makes the pitch easier to believe.
- Pack the admin tools into the offer: Receipt capture, card controls, and Extend Pay give the reward practical value beyond the percentage.
In short, brands weighing a similar launch should ask whether the reward gives customers a reason to move more of their business over.
Our Take: Can a Famous Face Keep a Customer?
Fame can earn an owner's attention for a few seconds, but it's up to the offer to hold it after that.
We think that Alba can win the first look and almost none of the renewals, because nobody falls in love with a statement credit.
Casting an actress who has met a payroll makes the pitch credible to owners who have done the same.
The test comes 90 days in, when a new cardholder decides whether to keep using Spend Management or drift back to a spreadsheet.
Receipt capture and card controls only retain customers if they are easier than the habit they replace.
U.S. Bank should watch six-month retention among new cardholders, because that number will say more about Alba's value than any awareness metric.
Looking to modernize financial marketing strategies to refine audience positioning and retention messaging?
Explore these Top Digital Marketing Agencies for Financial Services in our directory.